Threats to Auditor Independence
International Code of Ethics for Professional Accountants ACCA AA & AAA
Conceptual Framework
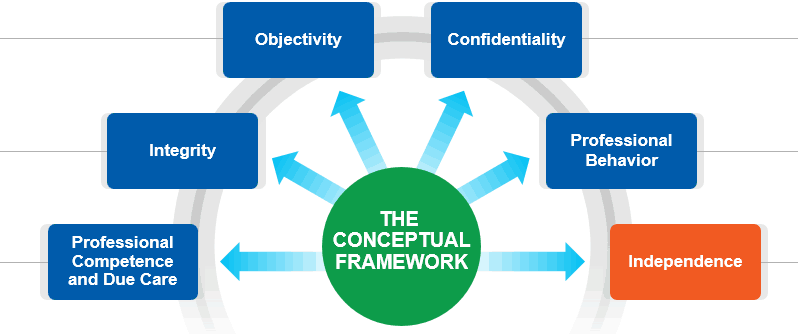
What is Auditor Independence?
Auditors are expected to provide an unbiased opinion on the work that they have performed. An auditor who has a lack of independence or has threats to auditor independence, his audit report useless to those who rely on it.
For example, consider yourself a potential shareholder in XYZ Company. If you know that the auditor for XYZ Company keeps a personal relationship with the CEO of the company, would you trust that the audited work is a fair representation of the company’s financial standing? How can you be certain that the auditor and CEO did not influence issues a favorable audit report? so must ensure that Auditor no have Threats to Auditor Independence
Once you have identified a threat from the question scenario, you will need to name the threat, explain WHY it is a threat to the auditor and tell the safeguard for that threat.
Here are a few techniques that can be avoided Threats to Auditor Independence,
Threats to Auditor Independence?
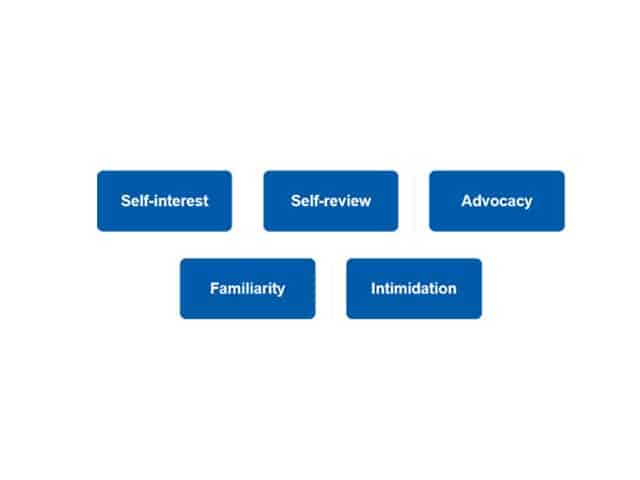
In Audit, there are five threats that hurt the independence of the auditor. Before the start of an audit engagement, it is crucial that each member of the audit team independence. If an auditor is exposed to a certain threat, He/she should either develop safeguards to reduce the threat to an acceptable level or resign from audit engagement. here we are going to discuss threats to auditor independence and possible remedies
QCR: Quality Control Review ( independent partner review)- Having a professional accountant who was not involved with the non-assurance service review the non-assurance work performed
Chinese walls: The use of separate engagement teams, with different engagement partners and team members
Public interest entities are:
- (a) All listed entities; and
- (b) Any entity:
- Defined by regulation or law-making as a public interest entity
- OR
- For which the audit is required by law and regulation to be conducted in compliance with the same independence requirements that apply to the audit of listed entities. Such regulation may be circulated by any relevant regulator, including an audit regulator
1. Self interest threat and safeguards
[table id=22 /]
2. Self Review threat and safeguards
[table id=23 /]
3. Familiarity Threat and safeguards
[table id=24 /]
4. Advocacy Threat and safeguards
[table id=25 /]
5. Intimidation Threat and safeguards
[table id=26 /]
6. Conflict of Interest Threat and safeguards
[table id=27 /]
ACCA Past Papers Attempt These past papers questions to check your understanding:
- Sept/Dec Hybrid 2015-Q1
- June 2015-Q1
- June 2014-Q3d
- Dec 2013-Q4c
- June 2012-Q3b,c
This is the detailed explanation on Threats to Threats to Auditor Independence, and how its work, don’t forget to give us feedback by commenting below
Read More: How to Pass ACCA P7 AAA
Find Us on Facebook